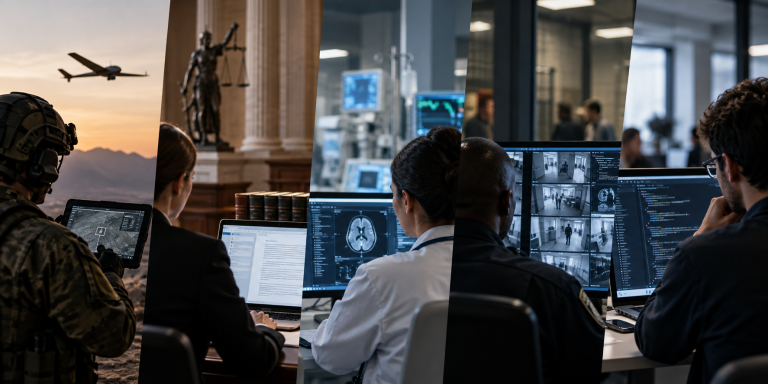
The first wave of generative AI minted household names and trillion-dollar hardware fortunes. The next one is quieter and more operational. It is happening inside law firms, hospitals, software orgs, defense programs, and correctional facilities—places that already have data, cameras, case files, and people who can be sued if the software is wrong.
That is the setup for the next valuation leg. The companies positioned for it are not only the labs shipping larger models. They are the ones turning those models into agents that sit on existing infrastructure, keep a human in the loop, and produce an outcome a partner, a physician, or a warden can defend.
Anthropic sits at the top of several 2026 private-company rankings. Claude is a default in enterprises that will pay for steerability and a cleaner safety story.
OpenAI still owns consumer mindshare and a massive API footprint. The open question is whether product breadth becomes lock-in once every competitor has a “good enough” model.
Google and Microsoft can drop frontier models into Search, Workspace, Azure, and Copilot overnight. In a cycle driven by deployment, distribution is a moat.
Nvidia remains the picks-and-shovels layer. Public-market AI exposure still starts with the company selling the accelerators.
xAI, now tied more tightly to SpaceX’s infrastructure story, is the scale-and-real-time-data bet. Databricks is the enterprise data plane that a lot of those models actually run on.
Those names will keep attracting capital. They are not the whole market.
Three filters separate hype from durable winners.
Agentic, not conversational. A chatbot answers a question. An agent watches a stream, correlates systems, drafts an action, and waits for a qualified human. The economic value is in the second category.
Domain infrastructure, not a greenfield app. The cheapest path to production is software that sits on cameras, EHRs, repos, matter files, and radios that already exist. Overlay-and-upgrade wins RFPs. Rip-and-replace loses them.
Defensible oversight. Regulated buyers will not purchase a black box that “decides.” They buy systems that surface an alert, preserve an audit trail, and require a professional before anything operational happens.
That is why vertical AI is starting to look less like a niche and more like the second act of the boom. Five companies show the pattern in different industries.
Anduril is the clearest example of AI leaving the chat window and entering a procurement system. Lattice, autonomous aircraft such as Fury, counter-drone command-and-control, and factory-scale production (Arsenal-1) are sold as finished capability, not a services contract. Revenue more than doubled to about $2.2 billion in 2025. In March 2026 the Army awarded a 10-year enterprise vehicle with a ceiling of up to $20 billion. In May the company raised $5 billion at a $61 billion valuation; later private marks have run higher as programs of record stacked up.
Why it fits the next run-up: national-security buyers are funding software-defined mass, not another PowerPoint prime. Switching costs after a program of record are measured in years.
Cognition’s Devin is not autocomplete. It plans work from requirements, writes and tests code, debugs, and ships inside a sandbox. Customers cited around the latest raise include Nvidia (chip-design workflows), GE Aerospace, Citi, Mercedes-Benz, and Goldman Sachs. Annualized revenue moved from about $492 million in May 2026 to roughly $900 million by September. The Series E was more than $2 billion at a $48 billion valuation.
Why it fits: every company is a software company, and coding is one of the few knowledge jobs where an agent can already close a loop. The market is not winner-take-all—Cursor proved that—but Cognition is priced as one of the two independent platforms that can own enterprise engineering agents.
Harvey started as “ChatGPT for lawyers” and is now a multi-model legal platform: research, contracts, diligence, litigation support, plus Tenet (a post-trained open-weight legal model) and Harvey LAB for agent evaluation. In September 2026 it raised $550 million at about $15.5 billion, with ARR past $400 million and more than 3,000 customers, including most of the Am Law 100 and a meaningful slice of the Fortune 500. It also bought Guardrails AI to harden agentic legal workflows.
Why it fits: law firms bill in six-minute increments and live on privilege, citation, and malpractice risk. A generic model that invents a case is a career event. A vertical stack that firms can put their own matter data into is a budget line.
OpenEvidence is the medical-knowledge layer a large share of U.S. physicians actually open during a shift. Answers are grounded in peer-reviewed literature and guidelines (NEJM, JAMA Network, NCCN, and others), not the open web. Usage has scaled into tens of millions of verified clinician queries per month; health systems such as UTMB have embedded it in the EHR. In 2026 the company launched a family of medical models (Osler, Sackett, Snow, and Darwin in research preview), partnered with Memorial Sloan Kettering to put OncoKB into broader oncology workflows, and announced a collaboration with Anthropic to extend access in lower-income countries. Private marks have been reported in the mid-teens of billions.
Why it fits: point-of-care medicine will not run on an uncited chatbot. The winner is the system doctors already trust, already have inside the record, and can point to when a quality committee asks “where did that come from?”
LEO Technologies (LeoTech) builds AI only for corrections and public-safety agencies. The Verus platform treats inmate communications, video, voice biometrics, and operational data as one layer instead of four vendors. In July 2026 it launched Verus Vision AI, which turns existing facility cameras into an agentic video feed, and Verus Voice AI, which uses voice biometrics to flag PIN abuse, identity fraud, and unauthorized communications. Verus ION is the investigative piece: correlating comms, biometrics, video, and legacy systems so a case is not assembled by hand. Built-in review by qualified staff is part of the product, not a disclaimer. Reporting around a multi-year Federal Bureau of Prisons award for AI-enabled translation and transcription of authorized inmate communications is the kind of reference other agencies copy.
Why it fits: corrections already paid for cameras and call systems. The budget that exists is for turning that infrastructure into operational intelligence without creating a liability event. That is a procurement problem general-purpose labs are not staffed to win.
Anduril sells autonomy into a defense budget. Cognition sells agents into an engineering org. Harvey sells cited work product into a partnership. OpenEvidence sells evidence into a clinical shift. LeoTech sells correlated awareness into a facility that cannot afford to miss a threat.
Different industries. Same architecture: domain data, existing systems, agentic workflow, human sign-off, contract that renews.
Frontier labs will keep raising and, in some cases, listing. Hardware vendors will keep selling every GPU they can make. That is the first tape.
The second tape is procurement. Once a general, a GC, a CMO, a VP of engineering, or a warden can point to hours saved, a pattern caught, and an audit log, the next budget line is easier than the first. Switching costs rise. Reference customers multiply. That is how vertical platforms go from “interesting startup” to “standard equipment.”
The companies that look expensive on current revenue often look cheaper on the workflows they already sit inside. Labs compete on benchmarks. These five compete on time-to-action inside a specific institution. That is the run-up still under-covered in most general AI roundups.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.